
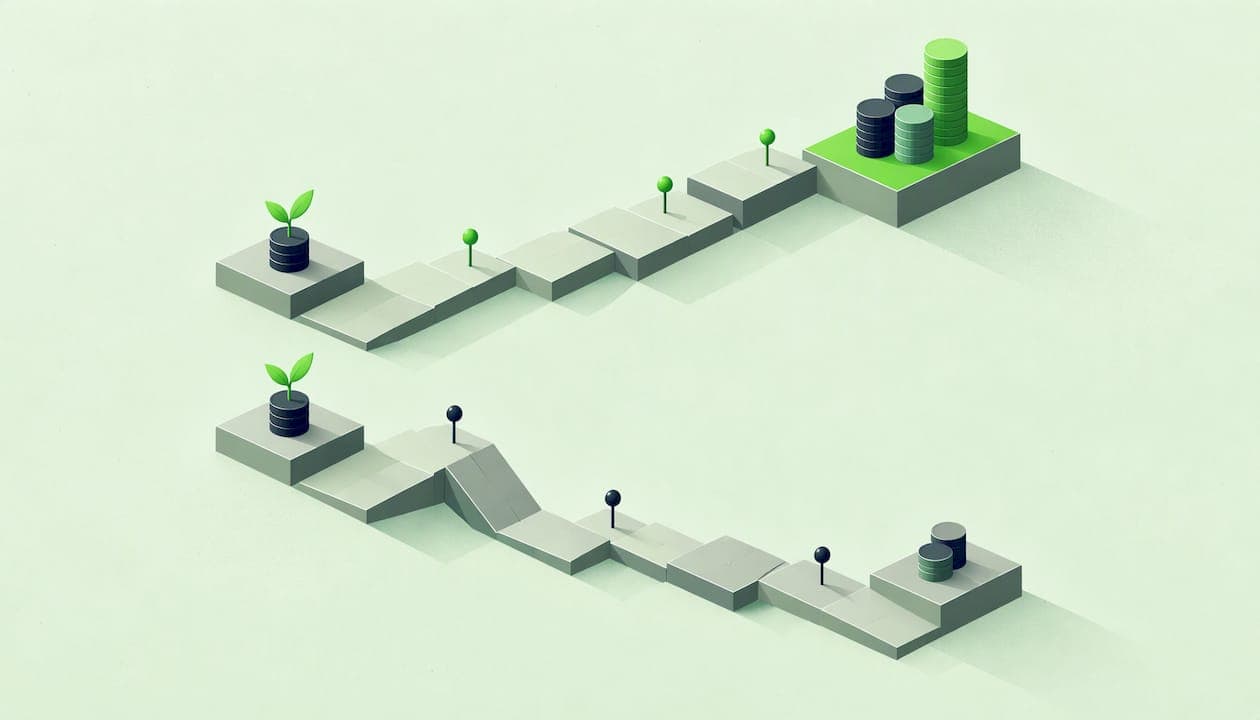
Sequence of returns risk is the danger that the order of your investment returns, not just their average, decides how long your money lasts once you start withdrawing from it. A bad market in the first years of retirement does far more damage than the same bad market twenty years in, because you are selling shares while prices are down and those shares cannot recover with the market. BlackRock's explanation puts the mechanism simply: withdrawals compound losses, since future returns compound on a smaller balance.
Below, you will see how the math works, what the research says about the danger zone, and the specific tools retirees use to defend against it.
TL;DR
- Two retirees with the same average return can end up in very different places if one hits losses early while withdrawing.
- The first five or so years of retirement are the most exposed, and the years just before retirement matter too.
- While you are still saving and not withdrawing, the order of returns matters much less.
- The main defenses are flexible spending, a cash or bond reserve, lower volatility early on, and guaranteed income sources.
- A rules-based portfolio that cuts stock exposure in weak markets is one way to put a defense into practice.
Table of Contents
- What sequence of returns risk means in plain terms
- A worked example: same average return, two outcomes
- Why the first years of retirement are the danger zone
- Does sequence risk matter while you are still saving?
- How to reduce sequence of returns risk
- Putting a rules-based process behind the plan
- Perspective
- Where StockPilot fits
- A simple checklist before you retire
- FAQ
- Sources
What sequence of returns risk means in plain terms
An average return hides the path. Suppose your portfolio earns 6% a year over 30 years. If you never touch it, it does not matter whether the good years come first or last: the ending value is the same. Once you take money out every year, the path becomes critical.
Here is the arithmetic, using round numbers for illustration only. You start with $1,000,000 and withdraw $50,000 at the start of the year.
- If the market then falls 20%, you hold $950,000 going in and end the year with $760,000.
- If the market instead rises 20%, you end the year with $1,140,000.
The gap after one year is $380,000, and the withdrawal in year two comes out of a much smaller base in the first case. Recovery is also harder than it looks: after a 20% loss, the portfolio needs a 25% gain just to get back to even, and that is before you take another withdrawal.
That is the whole idea. Losses early, combined with withdrawals, permanently shrink the pool of assets that can benefit from the recovery.

A worked example: same average return, two outcomes
Kiplinger walks through a hypothetical 30-year comparison. Two investors each start retirement with $1 million, withdraw $50,000 a year, and earn the same 6.3% average return. The investor who suffers three down years at the start sees the savings fall by nearly half and eventually run out. The investor who enjoys favorable early returns finishes with more than $2 million.
Nothing about the investors' skill, discipline or average return differs. Only the order changes.
BlackRock shows the same effect with a hypothetical $1 million portfolio and $60,000 annual withdrawals rising with 3% inflation. Return sequences with identical averages produce materially different results.
Why the first years of retirement are the danger zone
The risk is not evenly spread across retirement. It is concentrated at the start, for two reasons: your balance is at its largest, so a percentage loss is a large dollar loss, and you have the longest stretch of withdrawals still ahead of you.
The research backs this up:
- A 2010 paper on U.S. retirees who began in the early 2000s found that wealth remaining after 10 years plus cumulative inflation explained up to 80% of the variation in the final outcome after 30 years.
- Morningstar research, reported by CNBC in March 2025, found that a first-year decline of at least 15% combined with a 3.3% withdrawal raised the odds of running out of money within 30 years sixfold compared with a positive first year, assuming fixed future withdrawals.
- The same report describes the first five years of retirement as the stretch where withdrawals during a downturn hurt most, because fewer assets remain to benefit from a rebound.
Many planners call the years just before and after retirement the "risk zone" for this reason. A big loss at age 64 or 66 is far more costly than the same loss at 45.
Does sequence risk matter while you are still saving?
Mostly not in the same way. During accumulation you are adding money, not taking it out, and a market drop means your contributions buy more shares. BlackRock's illustration shows three hypothetical five-year return paths with the same 7% average ending at the same value when there are no additions or withdrawals.
What does matter near the end of accumulation is the size of your balance when withdrawals begin. A large loss in your final working years leaves you starting retirement with less, and you still have to fund the same spending. That is why people in their late 50s and early 60s start asking about allocation, not just contributions.
Target-date funds are the most common built-in answer. FINRA explains that they generally shift toward lower-risk assets such as fixed income and cash as the target date approaches, but glide paths vary by fund and the funds are neither guaranteed nor risk-free.
How to reduce sequence of returns risk
No single technique removes the risk. Most retirees combine two or three. Wade Pfau's academic paper on managing retirement income risk sorts the techniques into four approaches: reduce spending, adjust spending to portfolio performance, reduce volatility in early retirement, and draw from a buffer asset when the portfolio is down.
Start with spending, not the portfolio
CFP Matthew McKay told CNBC that understanding your spending needs is the most important starting point, rather than beginning with allocation alone. Separate essential costs (housing, food, insurance, healthcare) from flexible ones (travel, gifts, big purchases). If you can trim the flexible part after a bad year, you take less out of a depressed portfolio.
Withdrawal rate matters as much. The 2013 paper by Finke, Pfau and Blanchett cautions that a 4% inflation-adjusted withdrawal is not a guarantee: its estimated historical failure rate was about 6%, and modeled failure rates rose sharply when real bond returns were low. Our own look at evidence-backed sustainable withdrawal rates goes through where a base rate in the 3.3% to 3.9% range comes from.
Hold a reserve for near-term spending
The idea is to avoid selling stocks in a downturn by paying your bills from something steadier. CNBC reports a common bucket approach: one to two years of living expenses in cash, the next five years in short- to intermediate-term bonds or bond funds, and longer-term spending in growth assets.
A related idea is the bond tent. The Stable Value Investment Association describes raising low-risk assets near retirement and using them for several years of withdrawals, while leaving riskier assets invested for later recovery and growth.
How big should the cash piece be? It depends on the gap between your income sources and your spending. We cover the sizing logic in 3 to 24 months of cash by income gap, and the bucket structure in our rules-based four bucket plan.

Lower the volatility of the early years
A portfolio that falls less in a bad year gives sequence risk less to work with. Shifting part of the portfolio toward less volatile assets as you near retirement is the core idea behind adjusting allocation around the retirement date, and it is the same logic target-date funds apply. Pfau's paper also lists a rising-equity glide path, where you start retirement with a more conservative mix and gradually add stocks as the danger zone passes.
Add guaranteed income
Pfau's examples also include delaying Social Security to get a larger check, buying a lifetime-income annuity, and using buffer assets such as a reverse mortgage or whole-life insurance. Each covers part of your spending with money that does not depend on the market, so a market drop forces fewer withdrawals. Each has its own costs and terms, so a fee-only fiduciary adviser or CFP can model them against your numbers.
Quick comparison
| Approach | What it does | Best suited to |
|---|---|---|
| Flexible spending | Cuts withdrawals after bad years | Retirees with discretionary spending |
| Cash and bond reserve | Pays bills without selling stocks low | Anyone drawing regularly from a portfolio |
| Bond tent or glide path | Lowers volatility around the retirement date | People within 5 to 10 years of retiring |
| Guaranteed income | Covers essentials without market exposure | Those with a large essential-spending gap |
| Rules-based risk management | Reduces growth exposure when conditions weaken | Self-directed investors who want a process |
Putting a rules-based process behind the plan
The weak point in most plans is behavior. Retirees say they will de-risk when markets turn, then freeze, or sell at the bottom. A written set of rules that fires on conditions rather than emotion helps. Our seven rules-based ways to limit drawdowns lay out what that can look like.
Income also changes the picture. A portfolio that produces dividends can cover part of your spending without selling shares, which reduces how much you have to liquidate in a down year. Our three sleeve retirement income model and the bucketed, tax-aware version for retirees show how we think about this. If you are weighing the traditional alternative, see how 60/40 compares with an equity income approach.
Perspective
Sequence risk is a problem of timing and behavior, and both can be addressed with a process. We built StockPilot around a 19-position model portfolio: six income-producing positions and 13 AI-selected growth positions. The income side is there to support cash flow, and the growth side is there to pursue returns above the S&P 500.
The part that speaks most directly to retirees is risk management. When market conditions turn unfavorable, the system can reduce growth exposure and shift capital toward Treasury ETFs, according to predefined criteria rather than a gut feeling at the worst moment. You receive after-hours buy and sell alerts only when those criteria call for a change, so you are not watching screens or chasing stock picks.
You mirror the portfolio in your own brokerage account, and you keep control of every trade. We do not take custody, and we do not promise outcomes: all investing involves risk, and our risk disclosure explains ours in full. What we offer is structure for position sizing, replacement decisions and ongoing management, so that your plan for the early years of retirement is written down before the market tests it.
David Elliot
Where StockPilot fits
If you manage your own accounts and want a defined process for growth, income and downturn management, StockPilot Premium is $147 per month. You get the 19-position model portfolio, after-hours alerts, position sizing guidance and performance analytics, and you place every trade yourself in your own brokerage account. See how it works or go straight to StockPilot Premium.
It pairs with the rest of your plan rather than replacing it: your spending rules, your cash reserve and your guaranteed income still do the heavy lifting. For a candid view of the role of automation, read what AI investing can and cannot do for retirees.
A simple checklist before you retire
- Add up essential and flexible spending, then compare essential costs with Social Security, pensions and other guaranteed income.
- Choose a starting withdrawal rate and decide in advance what you will cut after a down year.
- Size a cash and short-term bond reserve to cover the gap for the first one to two years, or longer if your gap is large.
- Decide how your allocation will change in the five to ten years around your retirement date.
- Write down the rules for selling and rebalancing so you follow them when markets are falling.
- Review the plan yearly with a CFP or fiduciary adviser, especially after a large market move.
FAQ
What is an example of sequence of returns risk?
Two retirees start with $1 million, withdraw $50,000 a year and earn the same 6.3% average return over 30 years. In Kiplinger's hypothetical, the one with three early down years runs out of money, while the one with strong early returns ends with more than $2 million. Only the order of returns differs.
How do you mitigate sequence of returns risk?
Most retirees combine several tools: flexible spending, a one to two year cash reserve, a bond allocation for the next several years of needs, lower volatility around the retirement date, and guaranteed income such as delayed Social Security. A rules-based process for reducing risk in weak markets can support these steps.
Does sequence risk affect me if I am still working?
Less so. While you are contributing and not withdrawing, the order of returns has little effect on the ending value. The risk grows as retirement approaches, because a large loss shortly before you retire leaves you starting withdrawals from a smaller balance.
How long does the danger period last?
Morningstar describes the first five years of retirement as the most dangerous stretch for withdrawals during a downturn. Many planners also include the few years before retirement. After that, the portfolio has typically had time to recover or has already been adjusted.
Sources
- Kiplinger: Don't Let Sequence of Returns Risk Ruin Your Retirement
- BlackRock: Sequence of returns
- MPRA: Will 2000-era retirees experience the worst retirement outcomes?
- CNBC: Sequence of returns risk can hurt retiree portfolios (March 20, 2025)
- CNBC: Market volatility and retirement: Sequence of returns risk
- FINRA: Save the Date: Target-Date Funds Explained
- SSRN: The Four Approaches to Managing Retirement Income Risk
- SSRN: The 4 Percent Rule is Not Safe in a Low-Yield World
- Stable Value Investment Association: Using Stable Value in Retirement